Use the evidence and practical questions in this article to test your own assumptions. Any worked examples use hypothetical inputs.
Separate receiving evidence from being insured
A certificate holder receives evidence of insurance. An additional insured may receive protection under another party’s policy when the policy language and endorsements provide it. Those are not interchangeable labels. Being named in a certificate-holder box does not automatically make a customer, landlord or project owner an insured. Start with the written project requirement and ask the broker to identify the exact policy provision that would respond to the intended risk.
Check the scope of any endorsement
Ask whether the endorsement names a party specifically or operates under a blanket provision with conditions. Check the work, location, relationship and time period it covers. Ongoing and completed operations can raise different questions, and limits or exclusions may still apply. A contractual demand for protection does not prove the policy supplies it. If the requirement is unclear, have the contract and insurance reviewed together instead of asking for a broad phrase to be added to a certificate.
Use a project-specific evidence table
In a hypothetical fit-out, list the tenant, landlord, contractor and subcontractors separately. Record each party’s contractual role, requested status, supplied endorsement and reviewer. This prevents a certificate issued to the property manager from being mistaken for protection of every entity in the ownership chain. Verify exact legal names and do not invent an affiliation between similarly branded companies. Ask for a written explanation of unresolved scope before work begins or a deadline makes the review rushed.
Keep renewals and claims instructions usable
Save policy evidence with the relevant contract version, not in an unrelated email thread. Track expiration and material project changes that may require another review. Clarify how an incident is reported, who contacts the insurer and which documents should be preserved. Additional-insured wording is not a guarantee of payment in every dispute. It is one part of a broader review involving actual facts, applicable law, exclusions and the policy terms in force when the event occurs.
Record acceptance without broad promises
When the insurance reviewer accepts the evidence, retain the reviewed version and any limitations. Avoid relaying a broad statement that every party is fully covered. If the project changes, send the revised scope back for review rather than recycling the earlier acceptance.
Image source and usage
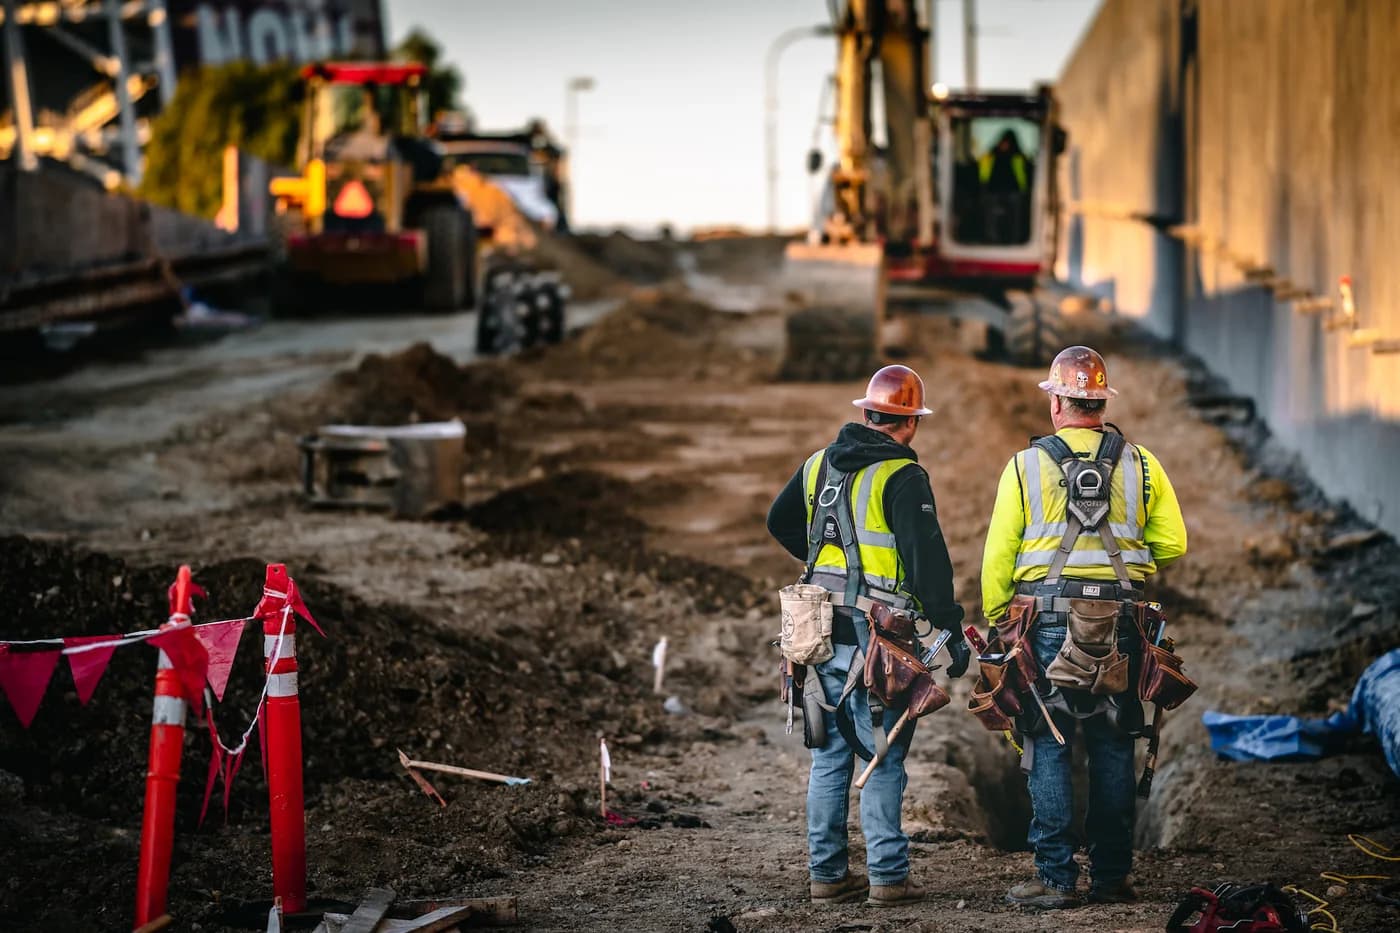
Construction workers on a site, photographed by Daniel Mekis
Boudoirphotographyguide
Source image · Image-use terms
Web versions are resized and compressed; attribution and applicable source terms are retained.
Frequently asked questions
Does certificate-holder status make me insured?
No. Confirm the policy and endorsement that grant any additional-insured protection.
Is a contract requirement enough?
No. Verify that the actual policy supplies the required protection and meets its conditions.
Sources & further reading
- Certificates of Insurance Frequently Asked Questions
- Launch your business - Small Business Administration
Source links checked October 23, 2026. Rules and availability may change; verify current terms directly. Read our editorial standards.