Close a working capital gap
Connect inventory, payroll and customer collections to a realistic repayment calendar.
The financing desk
Find the capital that fits the business you’re building.
Business loans, lines of credit, SBA financing and other funding routes, explained through the decisions that matter: purpose, cash flow, cost and the terms behind the offer.
Connect inventory, payroll and customer collections to a realistic repayment calendar.
Compare the project’s useful life with the term, deposit and total cost of funding.
Budget for the purchase and the cash the business will need after closing.
Separate opening costs, owner contributions and the reserve needed to reach stable trading.
Begin with the use of funds, then compare the repayment structure. The cheapest headline rate can still be a poor fit for the timing of your cash flow.
Program references cover the United States. Eligibility, terms and available products depend on the provider and jurisdiction. Official SBA program sources are linked below.
Beyond the headline rate
Put competing offers on the same sheet: the same amount of usable cash, the same spending purpose and the actual payment dates.
Understand the cost of capitalChange the assumptions to match your business. These tools are planning models; they do not quote lender terms or determine approval.
Model a monthly payment and total interest using your own loan assumptions.
Planning toolExplore debt service against cash available for repayments.
Planning toolMap collections, spending and the week a cash shortfall could appear.
Planning toolTest how pricing, variable costs and fixed spending change the sales target.
The application notebook
A useful application explains the amount, purpose and repayment source. Keep a consistent set of records and confirm the provider’s exact requirements before submitting sensitive documents.
50 articles
Business financing
A practical framework for comparing financing, stress-testing payments, and preparing before you apply.
Getting funded
A document checklist and a practical way to resolve inconsistencies before a lender reviews your application.
Business financing
Choose between recurring liquidity and a one-time investment by looking at the way cash returns to your business.
Financial fundamentals
Understand the cash-flow coverage calculation, its limits, and how to use it without treating it as an approval score.
Business financing
Map the cash conversion cycle and distinguish a temporary timing problem from an ongoing operating loss.
Growth & equipment
A practical checklist for matching repayment to installation, maintenance, and the equipment's useful life.
SBA financing
Understand the lender-based program and prepare questions before exploring SBA-supported financing.
SBA financing
Separate fixed-asset investment from broader financing needs before comparing program details.
Cost of capital
Learn to distinguish a repayment multiplier from an annualized borrowing cost.
Getting funded
Twenty practical checks to clarify the need, compare terms, and prepare for repayment.
Program briefing
How to prepare a documented project budget and questions for an approved microloan intermediary.
Working capital
Understand invoice financing and factoring, customer payment risk, reserve releases, and how to compare a funding quote.
Business planning
Build a weekly cash-flow forecast, separate receipts from revenue, test a downside case, and download your planning worksheet.
Growth capital
Build an acquisition funding plan around diligence, working capital, repayment capacity, and the actual loan agreement.
Funding options
Find official grant sources, check project eligibility and reimbursement timing, and keep unawarded funds out of your budget.
Credit preparation
Review business credit records, check reporting errors, document obligations, and prepare a financing request around repayment.
Entrepreneurship
Build a business plan around customers, operating decisions and a cash forecast. Includes a practical working template.
Entrepreneurship
Separate opening costs from recurring expenses and cash reserves. A worked startup budget shows where funding gaps appear.
Entrepreneurship
Turn customer interviews, competitor research and public data into a testable business decision, without confusing interest with demand.
Business economics
Calculate break-even sales from fixed costs and contribution margin, then test pricing, capacity and cash timing.
Business economics
A practical unit-economics framework for pricing, delivery costs, refunds and repeat purchases, with a worked example.
Business economics
Understand inventory days, receivables days and payables days. A worked example connects the cash conversion cycle to funding needs.
Technology
Assess supplier dependency, access, service continuity and exit options with a practical vendor risk review.
Leadership
Prepare a workable response to an outage, lost access or unavailable supplier. Includes a tabletop exercise and recovery checklist.
Entrepreneurship
Read a franchise disclosure document alongside the operating model, total investment and questions for existing franchisees.
Business economics
Compare acquisition spending with new customers, contribution and collection timing. Includes a worked CAC example.
Leadership
Build a focused KPI dashboard around cash, customers, delivery and operational risk, with explicit definitions and decision owners.
Leadership
Coordinate role expectations, access, training and feedback with an operational onboarding plan for a small team.
Leadership
Map business dependencies, decision authority and transferable records before planning an ownership or management handover.
Real Estate
Prepare the operating questions behind a commercial lease: space, costs, timing, permitted work and continuity.
Business economics
Organize earnings, assets, dependencies and liabilities before discussing business valuation with an adviser.
Business Economics
Calculate gross, operating and net profit margin, understand markup, and test how discounts affect profit with a downloadable worksheet.
Business Operations
Build a receivables aging report using due dates, reconcile balances, resolve disputes and plan collections with an editable worksheet.
Cash Management
Set a business cash reserve using collection delays, required payments and recovery scenarios instead of an unexplained rule of thumb.
Business Strategy
Compare cost-plus, value-based and competitive pricing, calculate discount economics and design a useful price test with a working template.
Business Operations
Calculate inventory turnover and days inventory outstanding, inspect slow stock and connect purchasing decisions with cash and service levels.
Business Growth
Calculate customer retention, separate acquisition from churn, compare revenue retention and plan a test using a downloadable cohort worksheet.
Leadership & People
Plan the role, full employment cost, payroll responsibilities and onboarding steps before hiring a first US employee. Includes a working checklist.
Business Banking
Compare business banking fees, deposit protection, payment timing and access controls using your actual transaction needs and an editable worksheet.
Business Security
Reduce invoice-fraud risk with independent bank-detail verification, payment approvals and a clear response process. Includes a verification log.
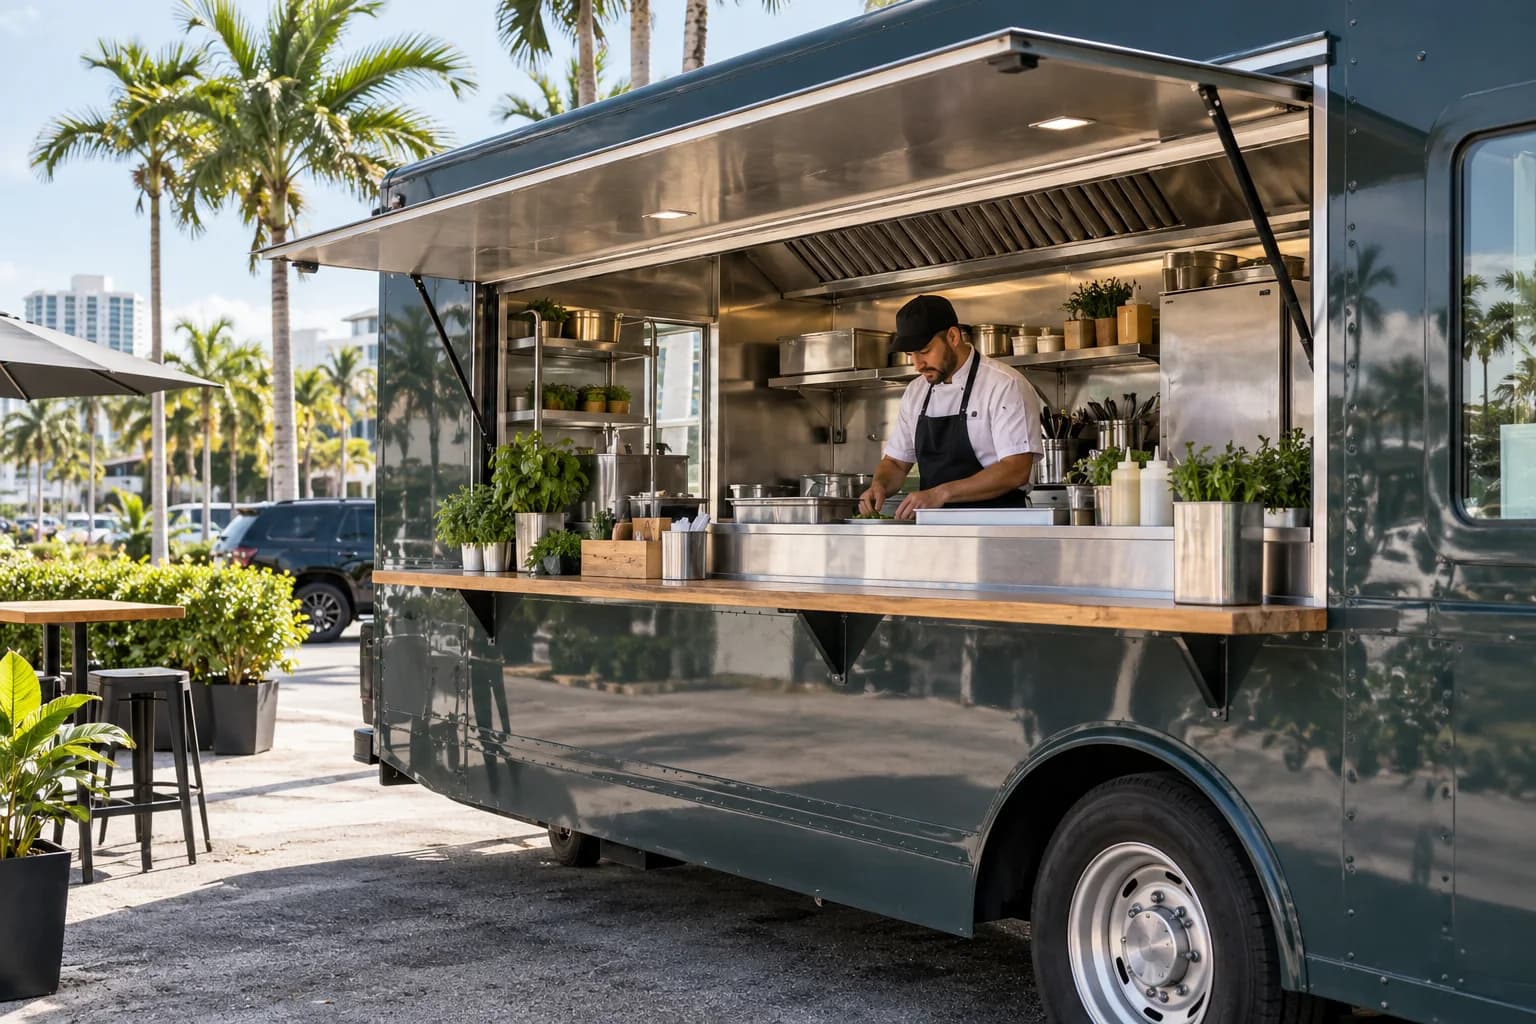
Small Business Startup
Build a Florida food truck startup budget with licensing checks, vehicle quotes, working capital and a break-even example. Includes an editable cost worksheet.
Business Operations
Create a small-business invoice that connects the agreed work, price, payment deadline and collection record without confusing estimates and receipts.
Business Operations
Separate purchase orders, invoices and receipts so approval, delivery, payment requests and collection can be matched without duplicate payments.
Business Operations
Calculate restaurant food cost using recipe yield, actual ingredient usage and waste, then compare gross contribution with the whole business.
Business Operations
Calculate a service-business hourly rate from billable capacity, operating costs and target compensation, then test overruns and collection.
Business Operations
Find your payment-processing effective rate from the full statement, separate fees from sales adjustments and compare equivalent providers.
US Trade & Operations
Calculate landed cost for a US import order with a worked example covering goods, freight, customs charges, handling and delivery.
US Trade & Operations
Map foreign exchange exposure for a US business and use a hypothetical currency example to separate price, conversion fees and timing risk.
US Trade & Operations
Write clearer international invoice terms covering currency, due dates, bank fees, payment method, beneficiary verification and disputes.
US Trade & Operations
Evaluate EXIM export credit insurance through buyer eligibility, covered risks, policy duties, cash flow and the difference between insurance and financing.
Local context
Our city and state resources connect local business context with public program references. A listed program is a research lead; check intake and eligibility with its administrator.
Start with what the money will pay for, when it will be needed and how it will be repaid. A one-time equipment purchase and a recurring gap between invoices and collections call for different comparisons. Review the full payment calendar and terms before deciding.
Read the business loan guideRequirements vary by lender and product. Prepare current financial records, a debt schedule, ownership information and an explanation of the use of funds. Cash-flow assumptions should connect to actual trading results. Ask the provider for its product-specific checklist.
Explore application requirementsA startup may have less operating history to demonstrate repayment. Build a startup budget, separate personal and business obligations and check each program’s actual eligibility. Equity, owner contributions, community lending and qualifying programs involve different costs and responsibilities.
Build a startup cost budgetA factor rate describes a repayment multiple, while an annual percentage rate expresses cost on an annual basis under its calculation rules. Comparing the two directly can be misleading. Ask for usable proceeds, all fees and the actual payment dates before comparing offers.
Understand factor rate vs. APROur guides explain financing structures and the questions behind a decision. Program details should be checked against the original source. We do not rank lenders by a promised approval rate or give individual suitability advice.