Use the evidence and practical questions in this article to test your own assumptions. Any worked examples use hypothetical inputs.
Spread maturities rather than guessing one perfect date
A CD ladder divides money among certificates of deposit with different maturity dates. Its purpose is to create planned access points while some funds remain in longer terms. It does not eliminate early-withdrawal penalties or guarantee a higher return than every alternative. Start with the money you can leave untouched and keep a separate reserve for expenses that cannot wait. FDIC guidance treats qualifying bank CDs as deposit products, subject to applicable insurance rules. A brokered CD or a product with special features needs its own review rather than being assumed identical to an ordinary bank certificate.
Build a simple hypothetical schedule
Suppose $12,000 is divided into 4 equal deposits of $3,000 with hypothetical terms of 3, 6, 9 and 12 months. The principal reaches an initial decision point every 3 months. At each maturity, you can use the money or consider a new term; reinvesting for 12 months can maintain a rolling schedule if the dates and available products fit. Interest, taxes and any different account terms need separate treatment. This example shows timing, not current rates or a recommended allocation. Write the actual maturity date for each certificate instead of relying only on a term label.
Review the decision before automatic renewal
Check the grace period, automatic renewal setting, new rate, minimum balance and early-withdrawal calculation before a certificate matures. A reminder should arrive early enough to compare choices and provide instructions. Review insurance concentration across deposits at the same bank and ownership category rather than treating each certificate as a separately unlimited insured account. If an upcoming expense changes the need for cash, alter the next maturity decision rather than assuming the original ladder must continue forever. The useful feature is an orderly process for access and reinvestment, not a promise that future rates will follow today’s pattern.
- Keep near-term expenses outside a schedule that could require penalties.
- Record maturity dates, grace periods and renewal instructions.
- Review insurance and new terms before reinvesting each deposit.
Image source and usage
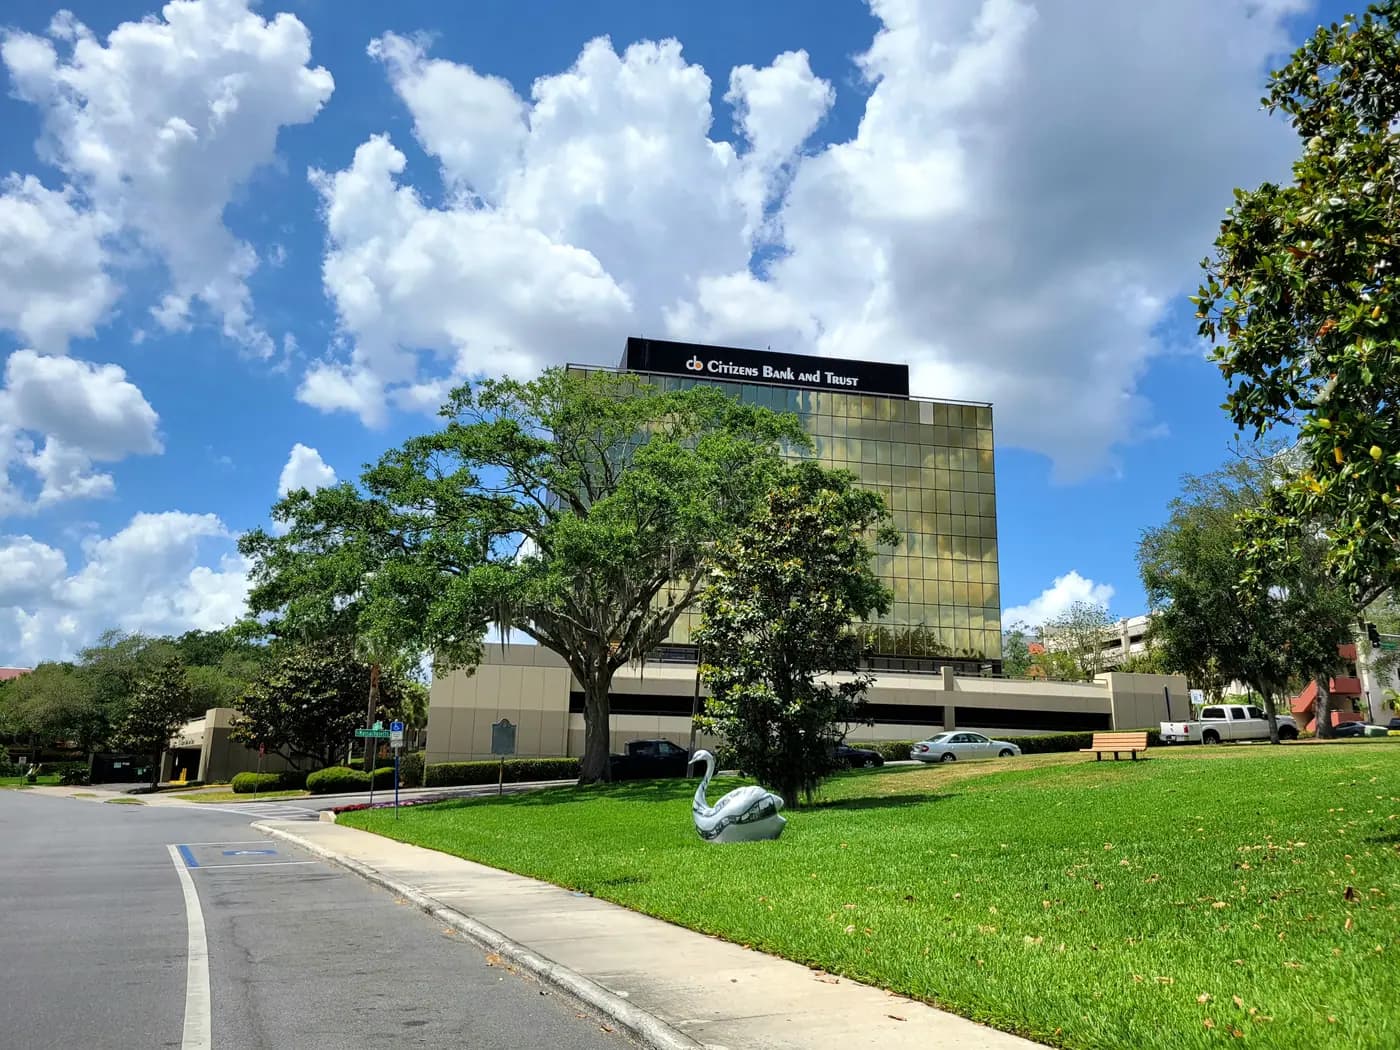
A Citizens Bank and Trust building in Lakeland, Florida, as a banking reference
Kiran891
Source image · Image-use terms
Web versions are resized and compressed; attribution and applicable source terms are retained.
Frequently asked questions
Does a CD ladder guarantee higher returns?
No. Results depend on rates, terms, timing, fees and alternatives. The ladder primarily organizes maturities and cash-access decisions.
Are early withdrawals always free at a scheduled interval?
No. A maturity allows a decision for that certificate under its terms; other certificates can still carry withdrawal penalties.
Sources & further reading
Source links checked October 20, 2026. Rules and availability may change; verify current terms directly. Read our editorial standards.