Read this report alongside the linked primary sources. Distinguish the announced event from its potential effect on your business.
The education-credit proposal
Treasury and the IRS issued proposed regulations on October 1 concerning the federal Education Freedom Tax Credit, with the program described as beginning in 2027. The release links qualified contributions to eligible scholarship-granting organizations and participating states. A contribution, a tax credit and a student scholarship are separate steps, so a family should not treat the announcement as an automatic tuition payment. The proposal creates a planning question for donors and organizations while the detailed rules and participation processes develop. Readers should identify which part of that process they are researching before relying on an advertised benefit or making a financial commitment.
Separate the donor’s file from the student’s file
A donor can ask how the organization’s eligibility is documented, which contribution period is relevant and what acknowledgment will be provided. A family seeking a scholarship needs different answers: the application process, qualifying expenses, selection criteria and payment arrangements. Keep those questions in separate lists so one organization’s fundraising language is not mistaken for a promise of aid to a particular student. A school’s acceptance of a child is also distinct from approval of scholarship funding. Before any contribution or enrollment decision, request the written conditions and verify the current official status of the organization and program.
Watch participation and final guidance
The most useful developments will be official participation information, organization listings and final guidance explaining how the program is administered. Preserve the version and date of any document used in planning because a proposal can evolve. If a promoter quotes a tax saving, ask which assumptions and limitations produce that figure and have the complete facts reviewed before treating it as certain. For an organization, build a record of responsibilities for donor acknowledgments, student information and use of funds. A program can attract considerable attention before its local operating process is ready; the practical task is to verify the steps that actually connect the donor, organization and recipient.
Image source and usage
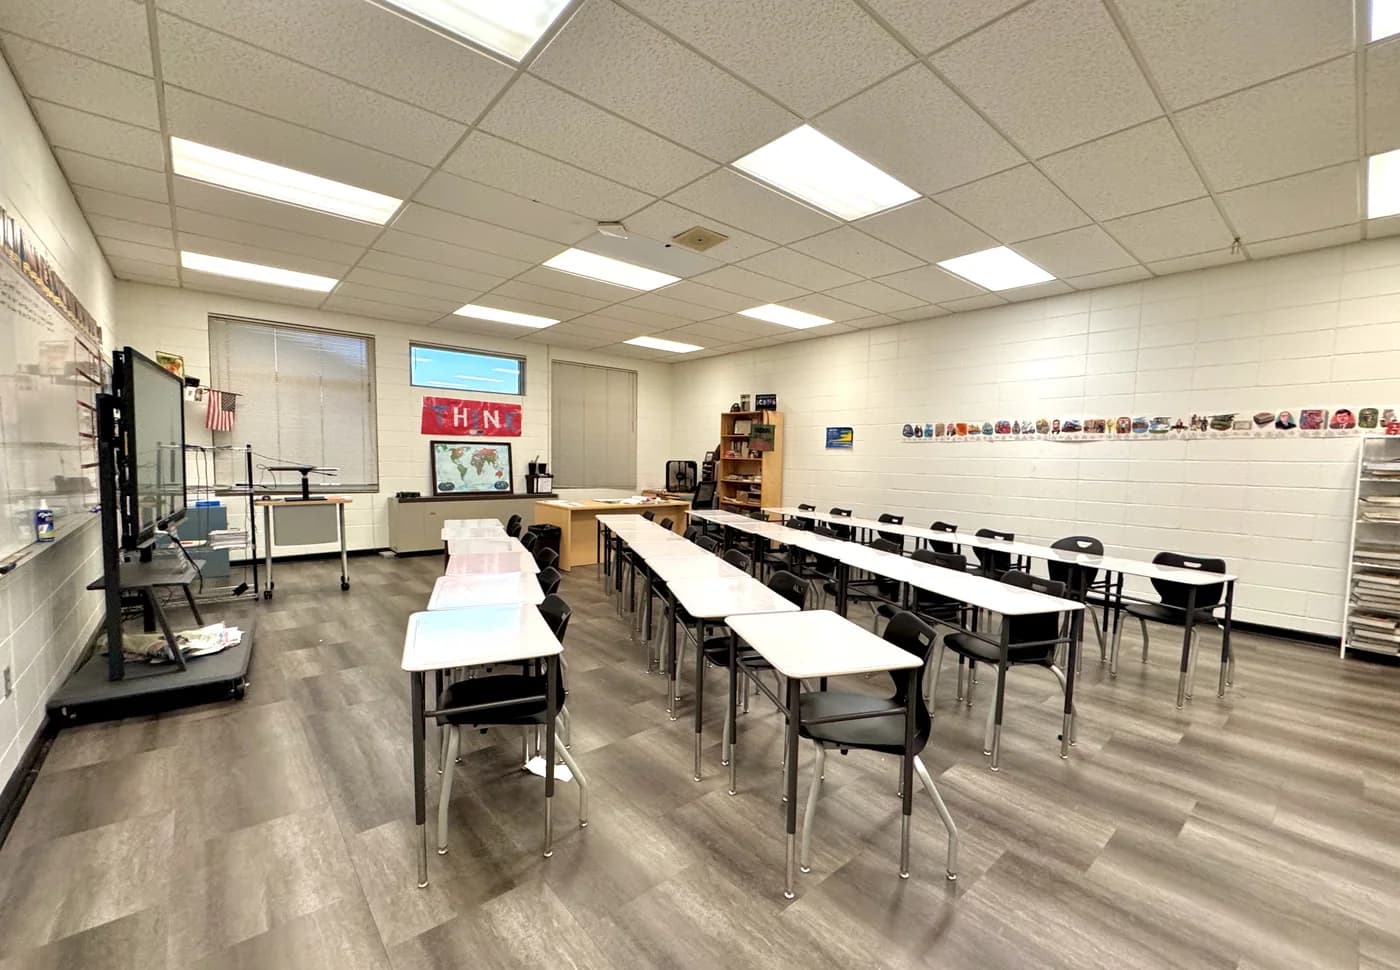
Reference photograph of a classroom at Hayesville High School in North Carolina
Harrison Keely
Source image · Image-use terms
Web versions are resized and compressed; attribution and applicable source terms are retained.
Frequently asked questions
Does the proposal guarantee a scholarship for my child?
No. Donor tax treatment, organization participation and student scholarship eligibility are separate questions that require current official rules and program documents.
Sources & further reading
Source links checked October 19, 2026. Rules and availability may change; verify current terms directly. Read our editorial standards.