Use the evidence and practical questions in this article to test your own assumptions. Any worked examples use hypothetical inputs.
Ask value and condition separately
An appraisal is an opinion of property value for the stated purpose, often used in mortgage lending. A home inspection examines condition within its agreed scope and reports findings for the client. A satisfactory appraisal does not prove that every system is sound, and a clean inspection does not establish market value. Ask who commissioned each report, what it covers and who receives it. Keep the lender’s valuation process separate from your own decision about repair risk and suitability.
Align the reports with contract rights
Review inspection, financing and appraisal provisions in the purchase contract with your adviser. Calendar the actual deadlines before ordering services. An inspection finding does not automatically let every buyer cancel or demand a price reduction; the contract and applicable law matter. Similarly, a value below the agreed price creates a financing and negotiation question, not one universal outcome. Ask what notice must be delivered, to whom and by when if a report affects your decision.
Budget follow-up beyond the base report
A general inspection may recommend specialist evaluation for roof, electrical, structural, pest or other concerns outside the initial scope. Obtain qualified follow-up and estimates rather than interpreting a photograph as a final repair diagnosis. For a hypothetical purchase, a modest inspection fee can reveal a much larger uncertainty that needs a separate decision. Review insurance inspections independently; wind mitigation and four-point reports serve different purposes from a comprehensive buyer inspection. Record what was inaccessible or not tested.
Keep a decision log instead of a pass label
List each material finding, specialist response, cost estimate and contractual decision. For the appraisal, review factual details and the lender’s process for correcting errors or reconsidering value when appropriate. Neither report guarantees future performance, freedom from hidden defects or a profitable resale. Preserve the final reports and any agreed repair documentation for the ownership file. A useful comparison lets the buyer see which uncertainty was examined, which remains and what action is required before closing.
Keep a specialist follow-up list
Mark each recommended follow-up as completed, declined or pending with the reason and deadline. A seller’s verbal repair promise is not the same as a completed repair record. Ask what evidence is needed before a final walkthrough and preserve any agreed changes in the transaction documents.
Image source and usage
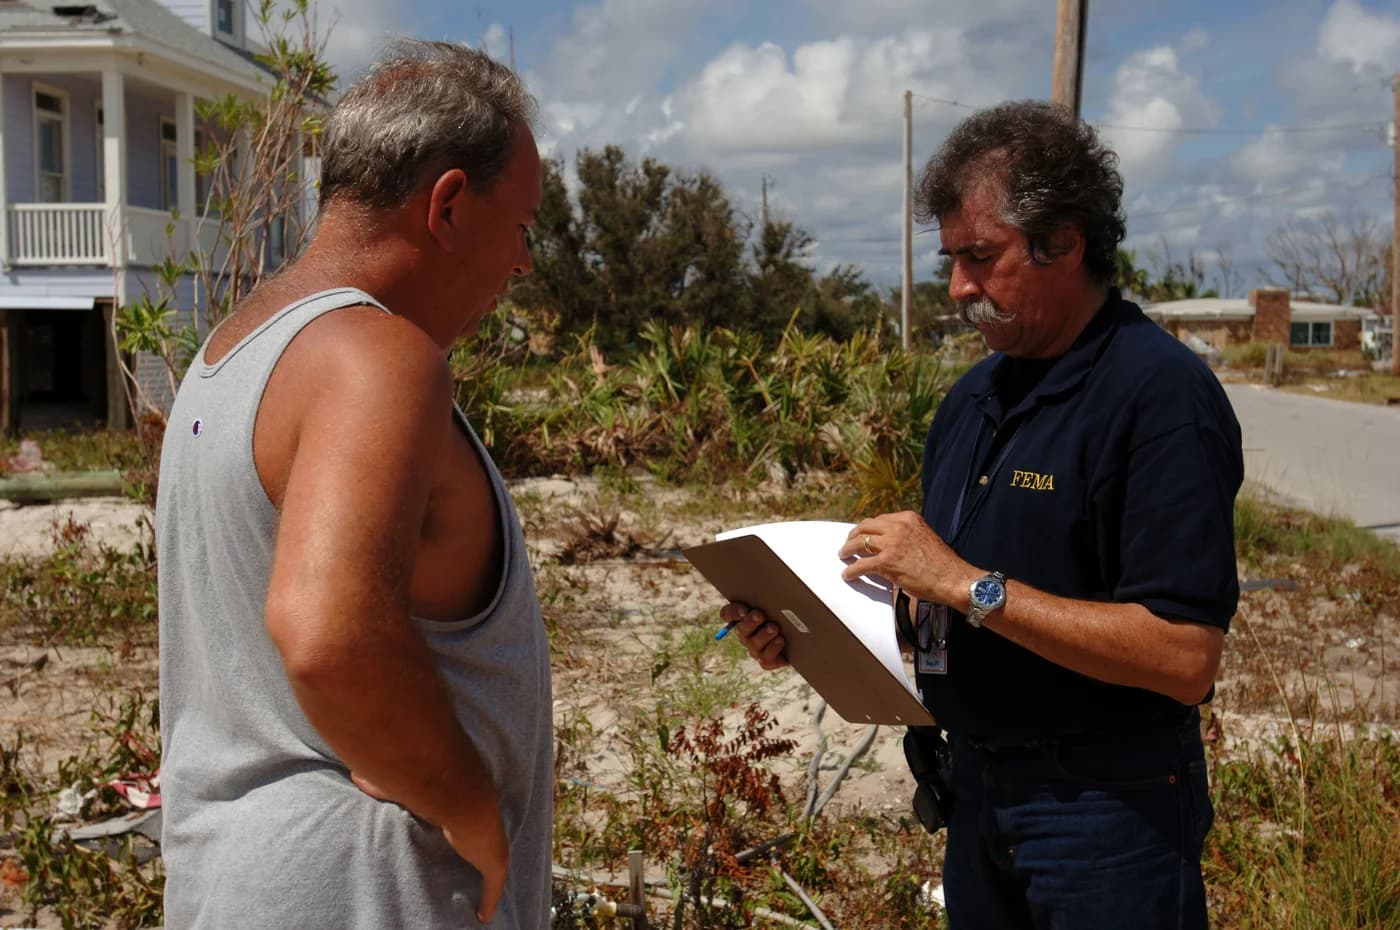
A FEMA property inspection in Florida, shown as a historic inspection reference
Jocelyn Augustino
Source image · Image-use terms
Web versions are resized and compressed; attribution and applicable source terms are retained.
Frequently asked questions
Does an appraisal replace an inspection?
No. Value and physical condition are different questions.
Does an inspection guarantee no hidden defects?
No. Read the scope, limitations, inaccessible areas and recommendations for specialist review.
Sources & further reading
- Schedule a home inspection | Consumer Financial Protection Bureau
- What are appraisals and why do I need to look at them? | Consumer Financial Protection Bureau
Source links checked October 23, 2026. Rules and availability may change; verify current terms directly. Read our editorial standards.