Use the evidence and practical questions in this article to test your own assumptions. Any worked examples use hypothetical inputs.
Ask which question the inspection answers
A wind-mitigation inspection documents features that may reduce wind damage and support eligible insurance discounts. A four-point inspection focuses on major systems such as roof, electrical, plumbing and heating or cooling for underwriting review. Neither is the same as a comprehensive buyer’s home inspection. Citizens describes these inspection categories separately, and other insurers may apply their own eligibility and form requirements. Ask the intended insurer what it will accept before paying an inspector.
Request the correct report and supporting evidence
Confirm the inspector’s qualifications, required form, photographs, inspection scope and expected delivery date. For mitigation, roof connections, opening protection and documented construction details can matter. For four-point review, condition and hazards can be more relevant than the home’s appearance. Do not infer a feature from a listing photo or assume an older report remains acceptable after a roof replacement. Provide permits, invoices and prior documentation when the inspector requests them, without asking for unsupported answers.
Budget for follow-up, not just the visit
A hypothetical inspection budget should separate inspection fees, specialist follow-up and any repairs needed for underwriting. A discount is not guaranteed simply because an inspection occurred, and an inspection does not guarantee the insurer will issue a policy. Ask the agent how findings affect the quote and whether corrective work requires another report. During a property purchase, align that review with contract deadlines so an insurance problem is not discovered after other decisions become difficult to reverse.
Keep grants separate from insurance discounts
My Safe Florida Home has its own inspection and grant eligibility, approved work and documentation process. A private inspection is not automatically a program inspection, and a potential insurance discount is not a grant award. Read the current program rules before starting improvements or assuming reimbursement. Keep reports, permits, contractor records and insurer confirmations together. Use the inspection to understand verified building features and next steps, rather than treating a favorable-looking form as proof the house is storm-proof.
Image source and usage
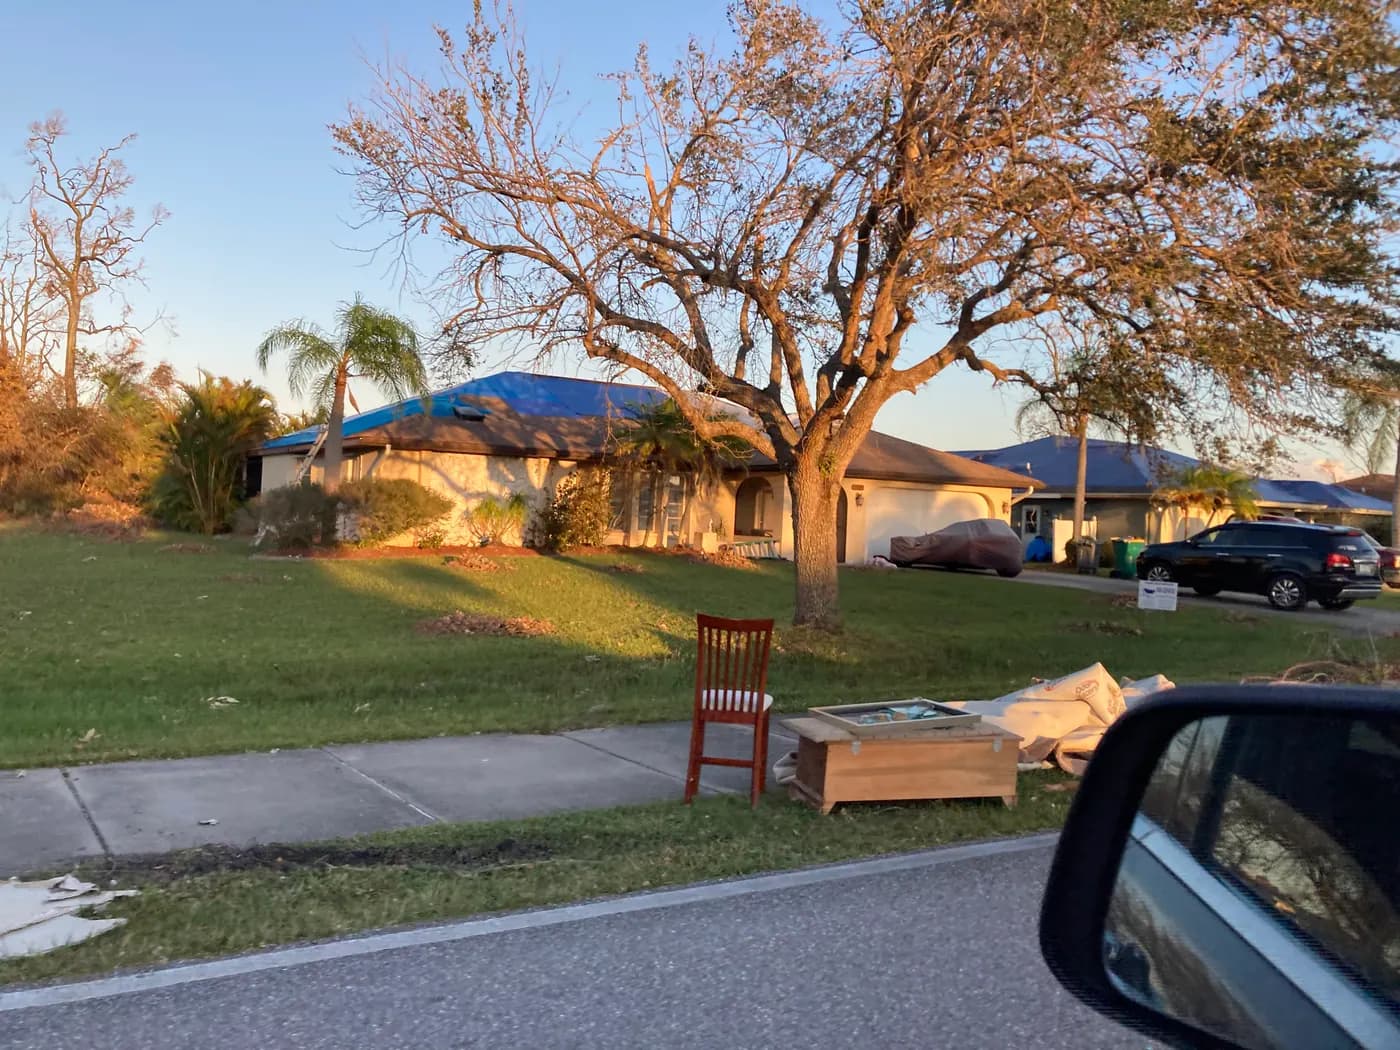
Historic roof damage in Deep Creek after Hurricane Ian
PCHS-NJROTC
Source image · Image-use terms
Web versions are resized and compressed; attribution and applicable source terms are retained.
Frequently asked questions
Does a four-point report replace a buyer inspection?
No. They have different purposes and scopes.
Is a mitigation discount guaranteed?
No. Eligibility depends on documented features and the insurer’s applicable requirements.
Sources & further reading
- Frequently Asked Questions - My Safe Florida Home
- Inspections - Public - Citizens Property Insurance Corporation
Source links checked October 23, 2026. Rules and availability may change; verify current terms directly. Read our editorial standards.